Taxation
Corporate and personal tax compliance and planning, with hands-on support when IRAS comes calling.
Tax services provided
- Corporate income tax return with computation (Form C, C-S, C-S Lite, Dormant)
- Tax filing of personal income tax (employee / sole-proprietor / self-employed)
- Tax filing for general partnerships / LLPs
- Withholding tax
- Transfer pricing
- Local tax incentives
- Estimated chargeable income (ECI)
- Assistance attending IRAS tax queries
- Certificate of Residence application (corporate / individual)
Tax planning that's actually reviewed
Every computation is checked line by line before it reaches IRAS — accuracy first, always.
Why businesses choose us for tax
Competitive Price
Transparent, upfront fees with no surprise billing.
Tailored Service
Tax planning scoped to your entity structure and cross-border exposure.
Fast Service
Timely filing ahead of IRAS deadlines, with responsive query support.
Reliable
ACRA-registered, ISCA-accredited standards of practice you can depend on.
Common tax questions
When are ECI and Corporate Income Tax Returns due?
Businesses in Singapore must file an Estimated Chargeable Income (ECI) within 3 months from the end of their financial year, unless they are specifically not required to file ECI or qualify for an ECI filing waiver. Corporate Income Tax Return must be submitted every year in compliance with IRAS filing requirements by 30 November, unless the company is dormant and has been granted a waiver to file its Corporate Income Tax Return.
How does Singapore's tax system treat cross-border transactions and withholding tax?
Interest, royalties and technical service fees are among the payments made to non-resident individuals or companies that are subject to withholding tax in Singapore. Rates can be reduced under an applicable Double Taxation Agreement (DTA) and are contingent upon the type of payment. Withholding tax must be filed and paid to IRAS by the 15th of the second month from the date of payment to the non-resident.
What are the penalties for non-compliance with IRAS transfer pricing guidelines?
Penalties for non-compliance with IRAS guidelines can be significant. IRAS may modify taxable profit and apply a five percent surcharge on the transfer pricing adjustment amount if related-party transactions are not priced at arm's length. In addition, a documentation non-compliance penalty could apply. Timely preparation and retention of transfer pricing documentation is mandatory for some taxpayers and highly recommended for others to mitigate risks in Singapore and abroad.
When must a Singapore business register for GST and what is the current rate?
A business must register for Goods and Services Tax (GST) in Singapore when its annual taxable turnover exceeds the S$1 million threshold, either retrospectively or prospectively, or if it chooses to voluntarily register. Singapore's prevailing GST rate is 9%.
Meet our tax team
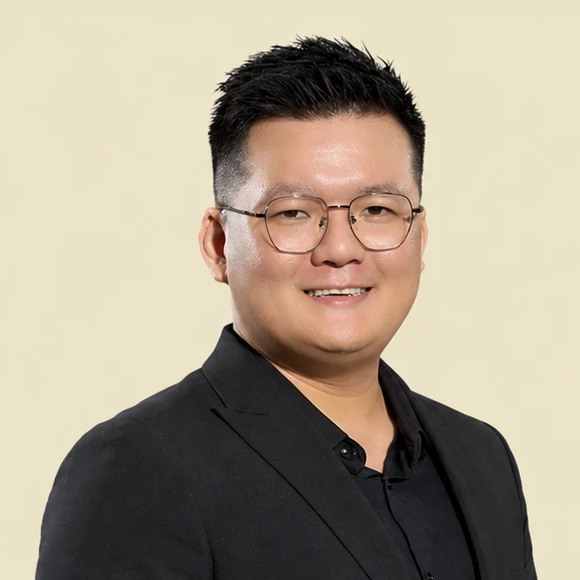
Kent CK
Head of Tax & Corporate Services
With 15 years of professional experience, Kent CK brings extensive expertise in tax advisory, corporate taxation, strategic tax planning, and business restructuring. Combining technical excellence with commercial insight, he delivers tailored solutions that enhance tax efficiency, optimize corporate structures, and strengthen financial performance. His strategic, forward-thinking approach helps businesses navigate complex tax environments, unlock growth opportunities, and achieve sustainable success in an increasingly dynamic global landscape.